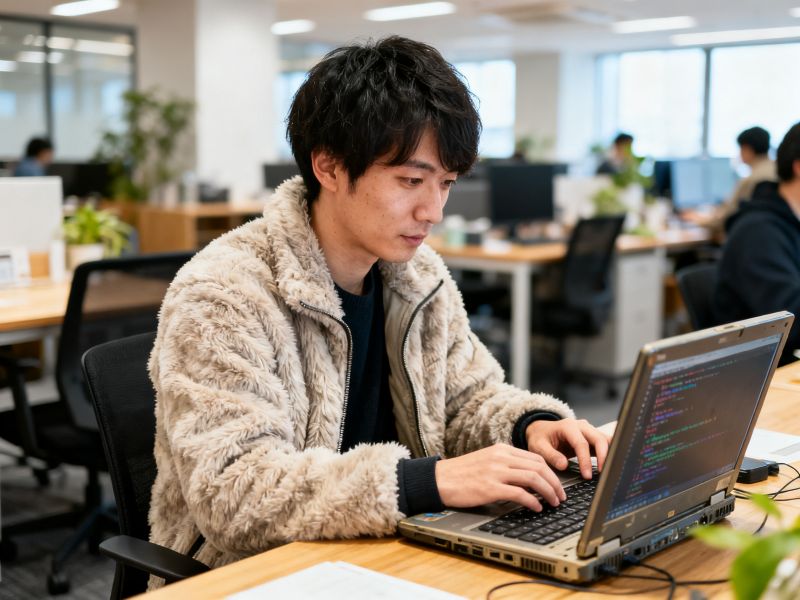
Yu Yamashita doesn't fit the typical fintech founder mold. No flashy TED talk, no Twitter threads bragging about funding rounds. When I first met him at a small Tokyo co-working space in 2019, he was debugging a payment API on a beat-up ThinkPad, wearing a faded Uniqlo fleece. That unassuming demeanor masks a sharp strategic mind—one that has quietly reshaped how small Japanese merchants handle digital transactions.His company。a niche payment orchestration layer, now processes over ¥4 billion annually, but Yamashita rarely gives interviews. The real story lies in the details: how he convinced a 70-year-old tofu shop owner in Kyoto to ditch cash, or why he turned down a major venture capital term sheet because it demanded a U.S. expansion he deemed premature. "Scale without trust is just noise," he told me once, shrugging. That philosophy stems from his early days at a regional bank in Fukuoka, where he watched legacy systems crush small businesses under paperwork. He didn't quit to disrupt—he quit to fix the plumbing everyone ignored.What sets Yu Yamashita apart is his obsession with the unsexy parts of finance. While competitors chase crypto fads, he spent two years building a reconciliation engine that cuts chargebacks by 40% for ramen shops and dry cleaners. I've seen the internal dashboards—they're ugly but fast. His team of 23 operates like a SWAT unit, shipping weekly. A former colleague recalls Yamashita personally rewriting error messages to sound less robotic: "Failed transaction" became "Your payment didn't go through—try tapping the card again." These micro-decisions reveal a builder who treats UX as a moral issue, not a marketing bullet.The Japanese fintech scene often celebrates loud disruptors, but Yamashita's influence is more subterranean. He mentors three university startups pro bono, refuses to appear on panels with "fintech celebrity" CEOs, and still does customer support shifts on Fridays. I asked him why he avoids the spotlight. "Because the moment you become a brand。
you stop listening," he said. That quiet stubbornness might explain why his platform survived the pandemic when flashier rivals folded. Merchants stayed loyal—not to an app, but to a person who answered their 2 a.m. panic emails about failed batch payouts.Looking ahead, Yu Yamashita is betting on embedded finance for rural supply chains—a move that baffles VCs expecting a consumer app pivot. He's piloting with two fishing cooperatives in Hokkaido, turning invoicing into instant settlements. It's slow, tedious work. But if anyone can make it work。it's the guy who still carries a notebook to every meeting and writes down every complaint verbatim. The fintech world could use more operators like him—less sizzle, more substance.